
Last updated August 25, 2026
Free visual inspection and a written scope of work before any mitigation begins - photos, moisture readings, and drying logs go in your claim file
The scope we write is the scope we bill. Anything new gets shown to you, in writing, before we touch it.
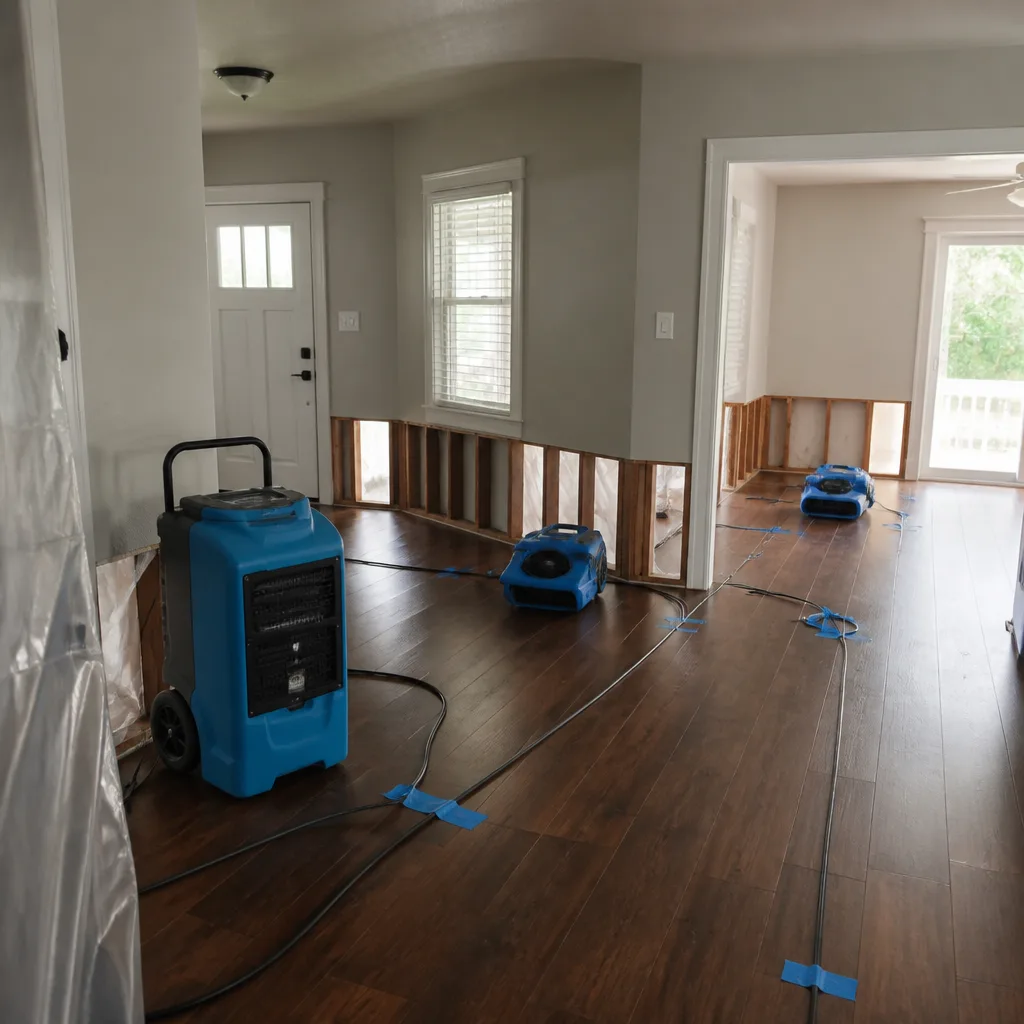
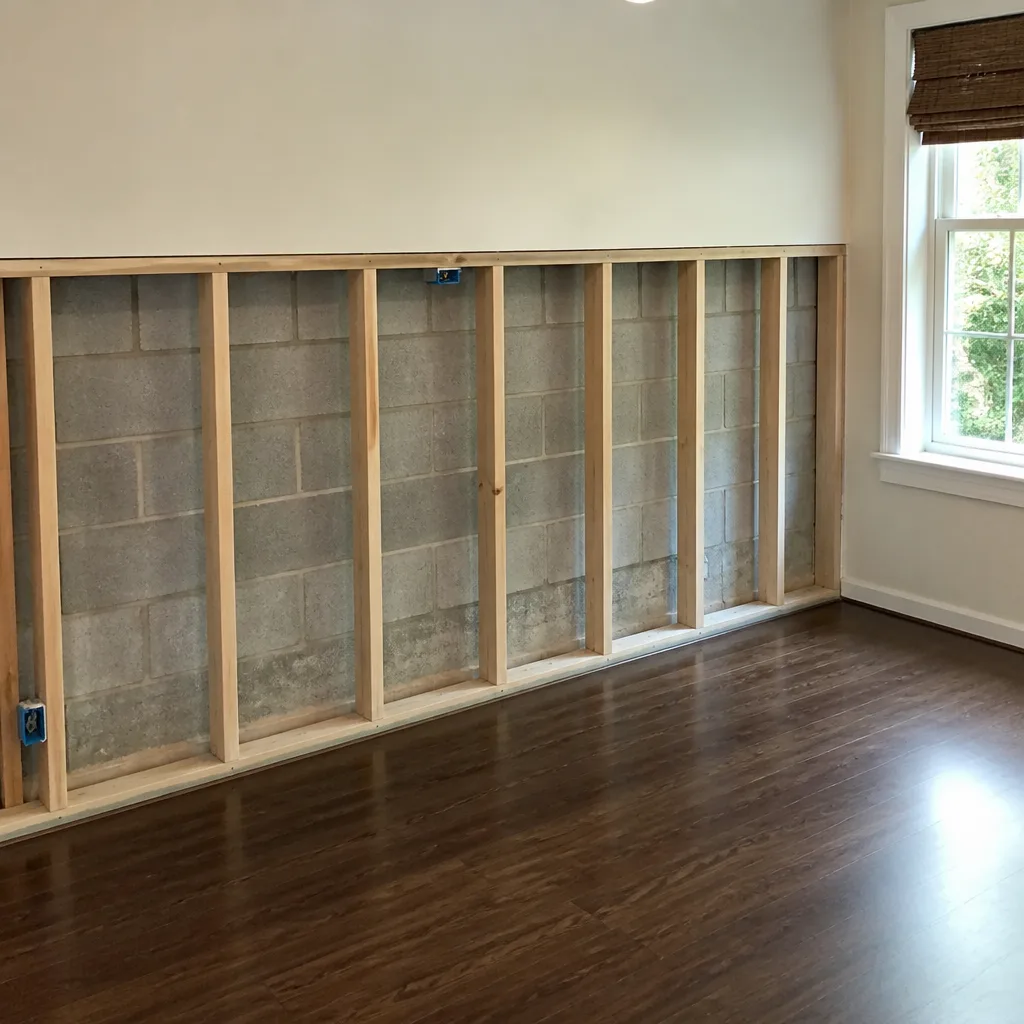
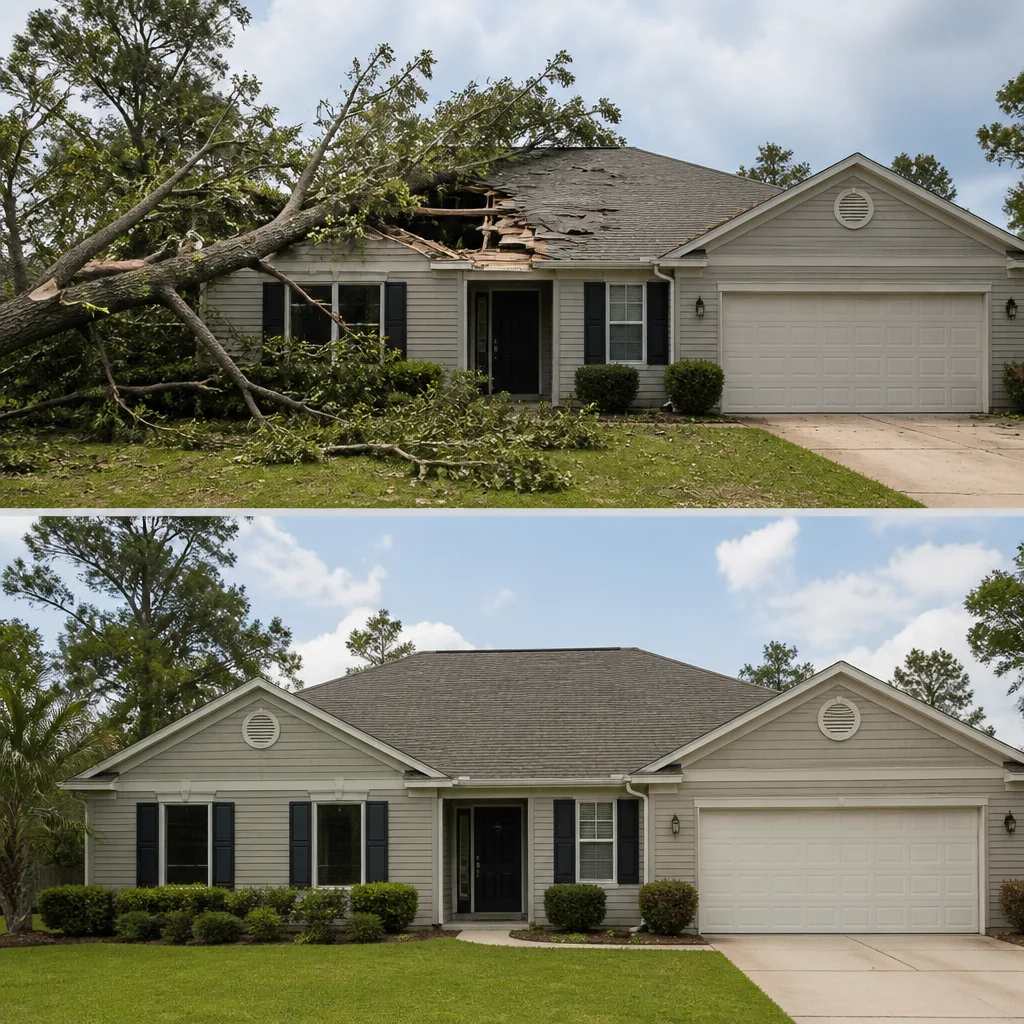
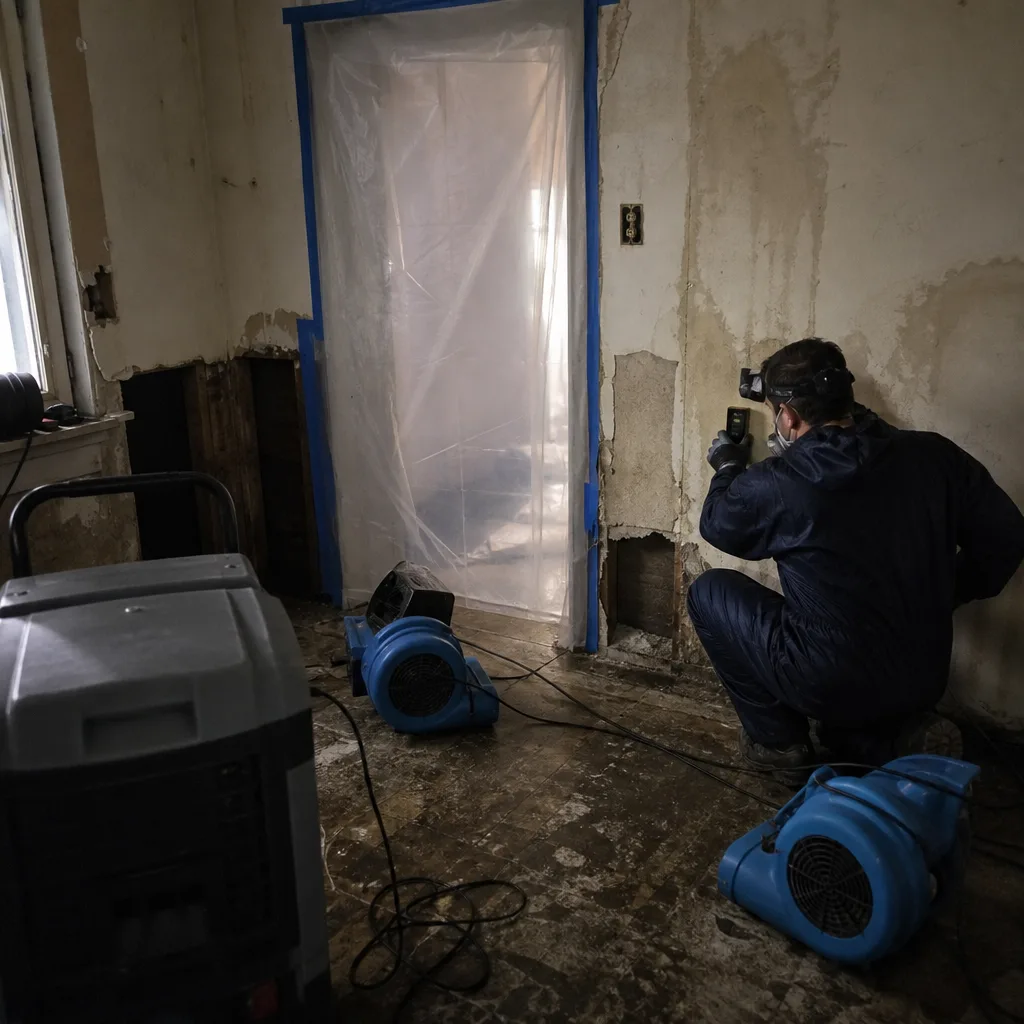 Before
 After
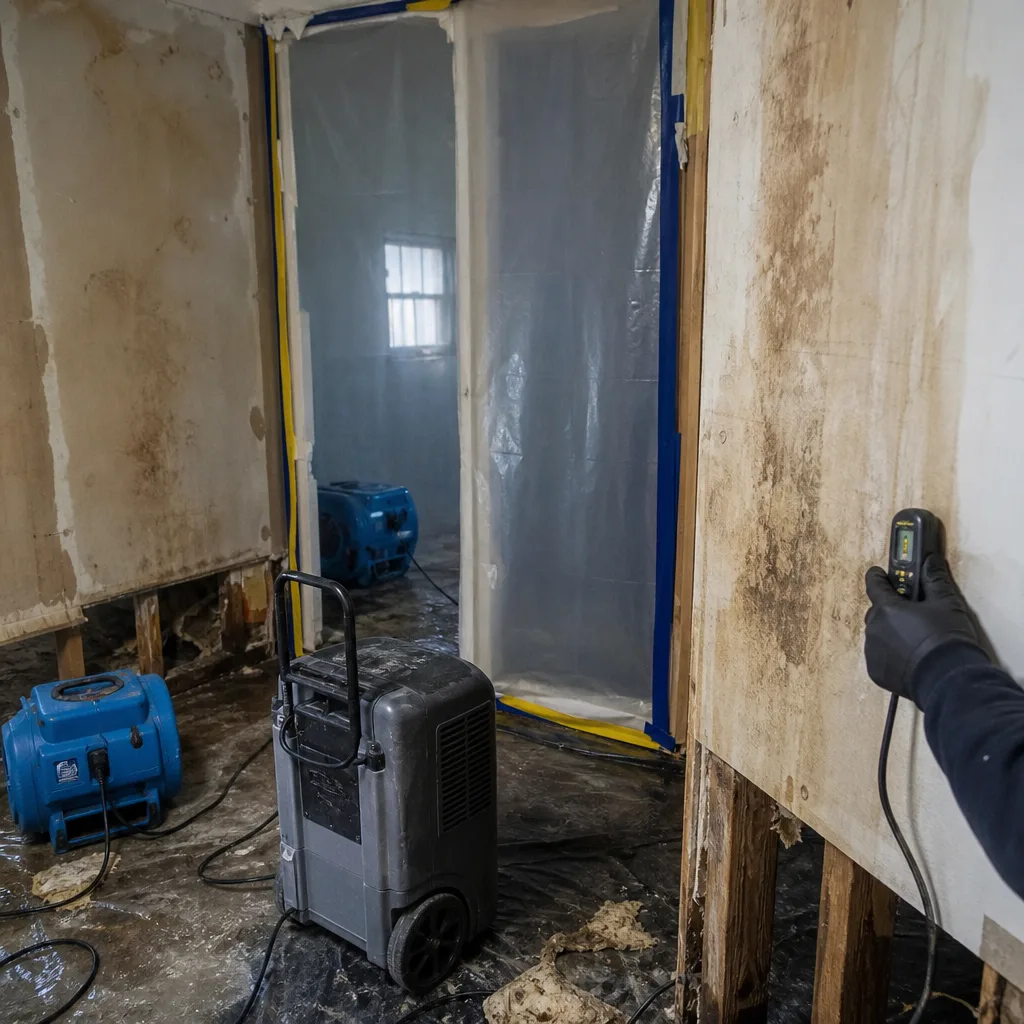 Before
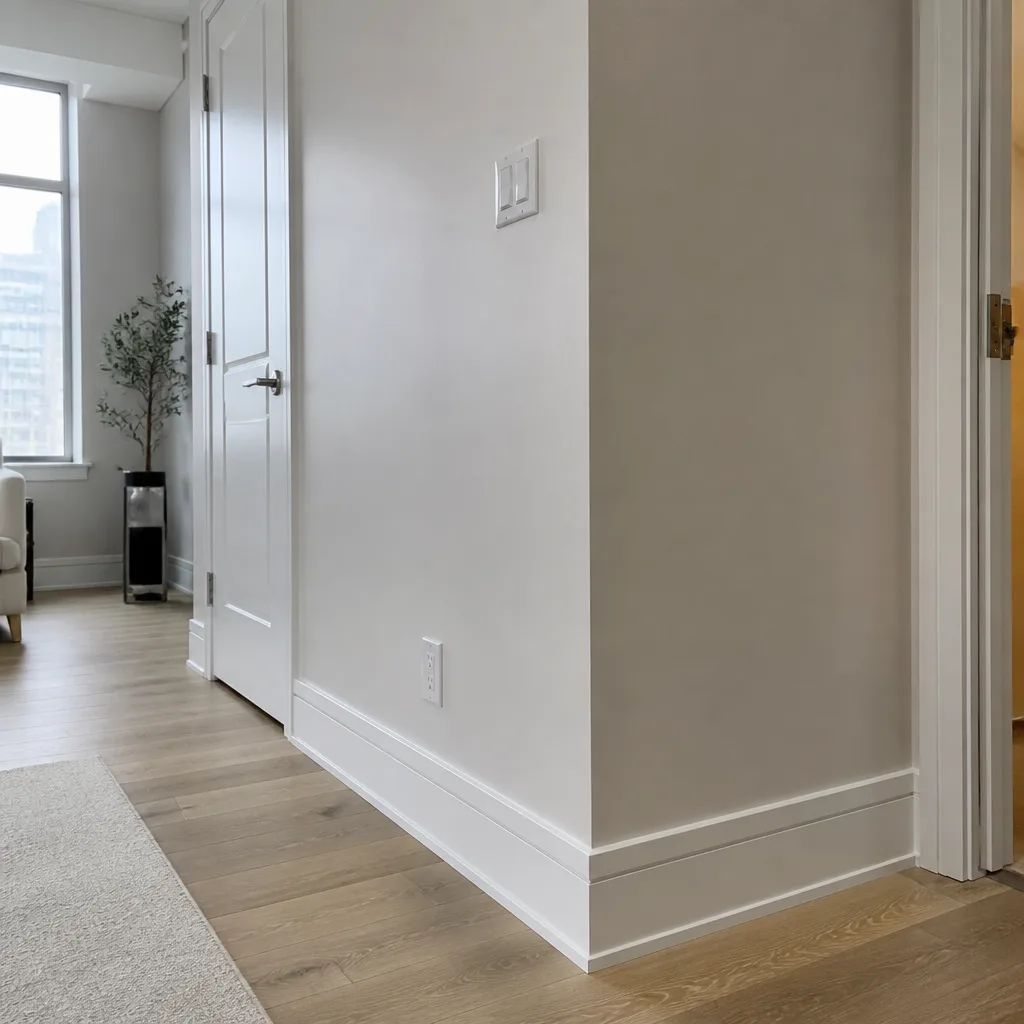 After
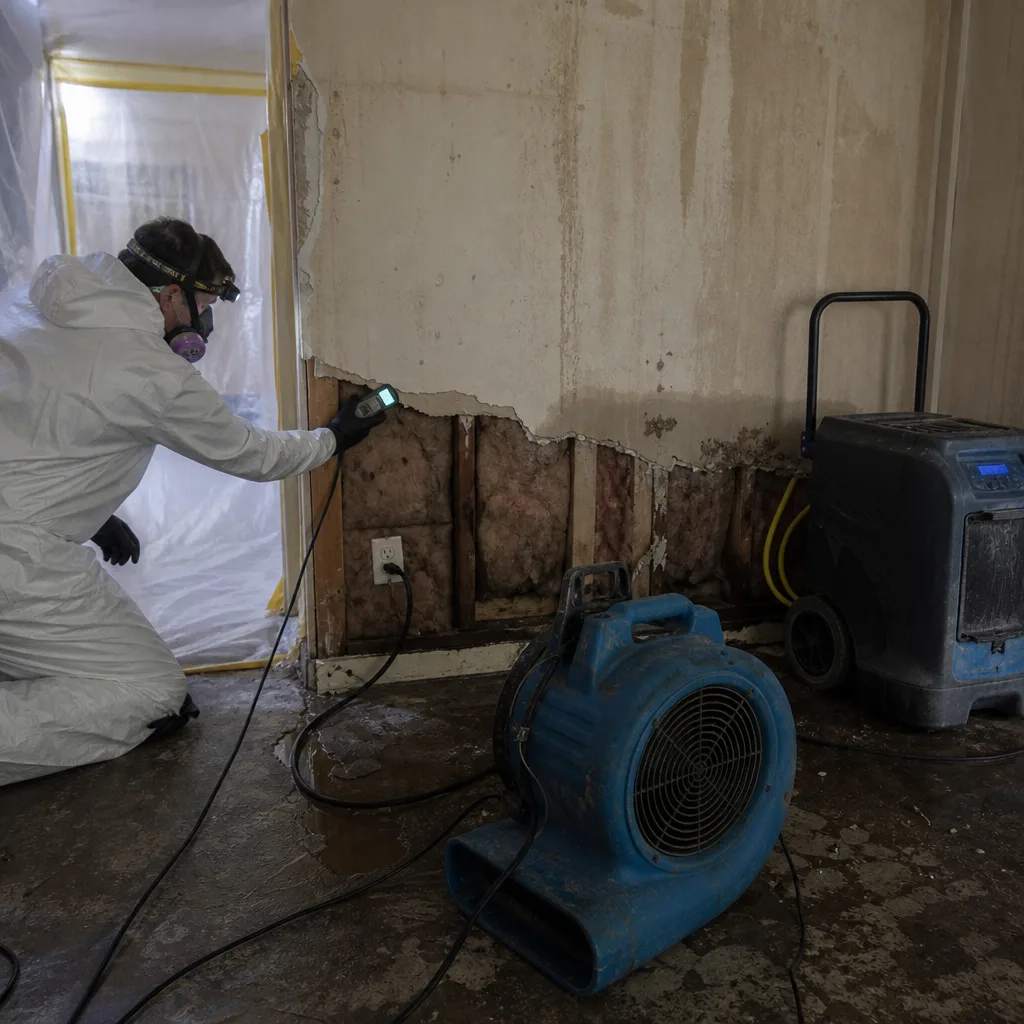 Before
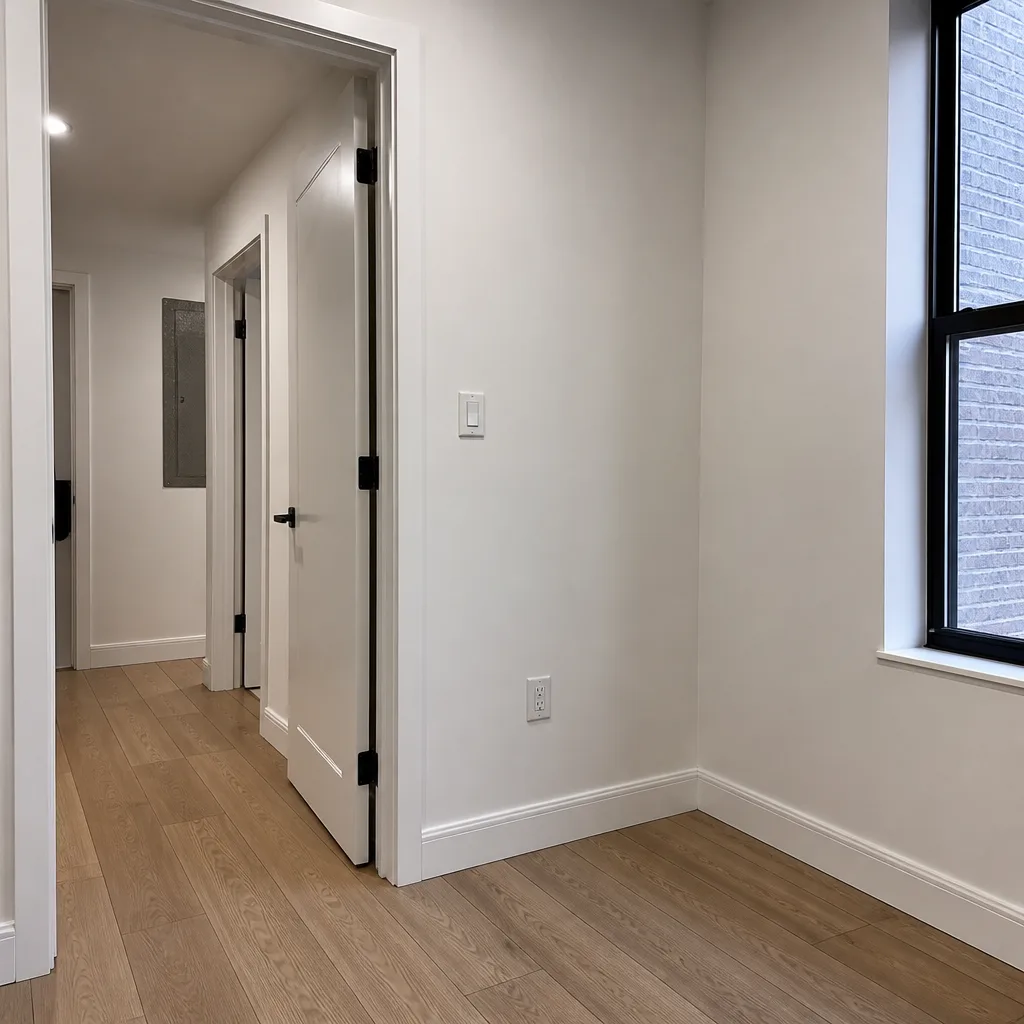 After
DIY vs Professional Damage Restoration: The Financial District Homeowner’s Decision Guide
In 2023, a Financial District condo owner spent $4,700 trying to dry out a bathroom leak with rental fans and a dehumidifier from a big-box store. Three months later, the ceiling below had to be opened anyway. The mold had spread behind the tile, through the subfloor, and into the joist cavities. The final professional bill: $18,300, most of which could have been avoided if extraction had started properly in the first 48 hours. This guide walks through what a homeowner can actually handle alone, what needs a certified crew, and how to tell the difference before the damage compounds. We’ll cover costs, equipment limits, insurance realities, and the specific risks that older Financial District buildings present.
Quick Answer
Most water damage in Financial District homes is not a genuine DIY project. If the water is clean, the area is small, the surface is non-porous, and you can dry it completely within 24 to 48 hours, a careful homeowner can manage it. Anything involving sewage, hidden cavities, drywall saturation, or standing water in a pre-war building should be handled by a certified restoration crew. The cost of professional equipment and moisture mapping is almost always less than the cost of a botched dry-out that turns into mold remediation.
Table of Contents
- Understanding the Real Scope of Damage
- What DIY Can Honestly Handle in a Financial District Home
- The Equipment Gap: Why Rental Machines Fall Short
- Hidden Moisture and the Financial District Building Stock
- Insurance, Documentation, and the Written Scope
- True Cost Comparison: DIY vs Professional Restoration
- Step-by-Step: What a Professional Restoration Actually Looks Like
- Common Mistakes to Avoid
- When to Call a Professional
- Frequently Asked Questions
- The Bottom Line
Understanding the Real Scope of Damage
Water damage in the Financial District rarely stays where you found it. The neighborhood’s building stock is dominated by pre-war construction: steel and concrete frames with plaster walls, often converted from commercial or warehouse use. Water travels down through floor assemblies, follows conduit and pipe chases, and pools above dropped ceilings. What looks like a stain on a wall may be the lowest point of a leak that started two floors up. Our crews have opened ceilings in Beekman and Cliff Street buildings and found water running along a beam more than 20 feet from where the homeowner first noticed discoloration.
That is the first reason the DIY decision is harder than it appears. The visible water is often a small fraction of the water that is actually present. A mop handles the puddle. The puddle was never the problem. The problem is what the puddle fed: drywall wicking, hardwood cupping, subfloor saturation, and the inevitable microbial growth that begins in any organic material that stays wet beyond 48 hours. In Financial District units with shared walls, that moisture can cross into a neighbor’s space, which turns a personal cleanup into a building-wide issue with co-op board or condo association involvement.
The second scope problem is contamination. Water falls into three categories under the IICRC S500 standard, which every legitimate restoration company works to. Category 1 is clean water from a supply line or faucet. Category 2 is gray water, meaning it contains some level of contamination: washing machine overflow, dishwasher discharge, toilet runoff without solid waste. Category 3 is black water: sewage, river water, storm surge, or any water that sat long enough to become biologically active. Category 3 is never a DIY project. It requires containment, antimicrobial treatment, and often the removal and disposal of affected materials. In Financial District high-rises, a backed-up waste line on an upper floor can send Category 3 water down through multiple units before anyone notices the ceiling bulging.
The final scope issue is time. The clock starts the moment the water is released, not when you discover it. A slow leak behind a kitchen cabinet may have been running for weeks before the cabinet base swells. By the time you find it, mold spores may already be established. That is why professional assessment begins with a moisture map, not with a fan. We need to know how far the water went, not just where it pooled.
What DIY Can Honestly Handle in a Financial District Home
There is a narrow but real band of damage a homeowner can handle without a professional. The threshold is specific and worth stating plainly:
- The source is stopped and verified clean. A shut supply line, a drained appliance, or a sealed plumbing connection. If you cannot confirm the water was clean and the source is fully stopped, call.
- The affected area is smaller than about 10 square feet. A puddle under a sink, a single cabinet base, a small section of tile floor.
- The surfaces are non-porous or minimally porous. Tile, sealed concrete, vinyl. Carpet and pad are usually disposable after saturation. Drywall almost always needs cutting.
- You can dry it fully within 24 to 48 hours. This means the area is dry to a moisture meter, not just to touch. Most homeowners do not own a moisture meter, which is one way to know whether this path is realistic.
- There is no odor of sewage or must. If you smell something, biological activity has begun. Do not try to clean it with bleach and call it done.
If every one of those conditions is true, a homeowner can do the following: remove standing water with a wet-dry vacuum, run fans and a dehumidifier for two to three days, wipe hard surfaces with soap and water, and monitor for odor or staining. That is the complete list. Notice what is not on it: opening walls, treating mold, drying ceiling cavities, or attempting to salvage saturated carpet. Those are not homeowner tasks in a Financial District building, and the reason is not gatekeeping. It is geometry. The areas you cannot see are exactly where water goes.
The Equipment Gap: Why Rental Machines Fall Short
The rental dehumidifier from a hardware store is a refrigerant unit. It pulls maybe 30 to 50 pints per day under ideal conditions, which in a cool, damp basement or a closed Financial District apartment is rarely the condition you have. A professional-grade desiccant dehumidifier like the ones our crews run pulls 100 to 150 pints per day across a much wider range of temperatures. The difference is not marginal. It is the difference between achieving a dry standard in three days versus two weeks. After two weeks, you likely have mold. You definitely have a claim adjuster asking why professional drying was not started on day one.
Air movement matters the same way. A box fan pointed at a wet wall dries the surface and not much else. Professional airmovers create laminar airflow across the surface, which accelerates evaporation from the material itself. Injectidry systems push air into wall cavities and under cabinets where water hides and rental fans cannot reach. This is specialized equipment, and it is expensive. A full professional drying setup for a master-bathroom flood can cost $10,000 to $15,000 in equipment alone, which is why homeowners rent. The problem is that the rental equipment is the weakest tier of the available technology, and it is being asked to do the hardest job.
Then there is moisture mapping. Our technicians take baseline readings across the affected area and the surrounding dry areas on day one, then take daily readings until the structure meets the dry standard. That log is the single most persuasive document in an insurance claim. It proves the water is gone and the job is complete. A homeowner with a rental fan has nothing equivalent. When the insurer later asks why mold remediation is needed, the homeowner has no log, no baseline, and no answer. That documentation gap costs more than the equipment rental saved.
Hidden Moisture and the Financial District Building Stock
Financial District buildings have specific failure patterns that a homeowner in a newer suburban house will never see. The brick and stone facades on many pre-war buildings are porous. Steady weather exposure over decades, combined with the neighborhood’s proximity to the East River and the harbor, means exterior walls can hold moisture long after a rain event. When an interior leak occurs, that latent moisture complicates the drying process. A wall that would dry in three days in a dry climate can take six in a Financial District unit on the water side of the building.
Concrete and steel construction creates thermal bridges. The concrete slab stays cold while the apartment is warm, and condensation forms at the transition points. When water damage occurs, these same slabs can wick moisture horizontally. We have seen water from a burst riser on Water Street travel through a concrete floor assembly and reappear as staining in a unit 40 feet away, on a different column line. Homeowners correctly suspect a leak in their own unit. The actual source was two floors up and across the hall. A professional with a thermal camera and penetrating moisture meters can read that migration. A homeowner with a rental fan cannot.
Raised floors are another Financial District condition. Many converted office and commercial buildings have raised access flooring, often with electrical and data cabling underneath. Water gets under the raised floor and sits in the plenum, out of sight, while the surface tiles look bone dry. We have pulled up raised floor panels in Financial District offices and found a half inch of standing water underneath. The owner’s vacuum had been running for two days on top of perfectly dry carpet tile. The water was never on the surface. It was under it, migrating.
The point is not that Financial District buildings are fragile. They are old, well built, and durable, but they were not designed for water extraction. They were designed long before anyone thought about moisture mapping or drying standards. When water gets into their concealed spaces, the building material itself becomes a reservoir. That is a professional condition, not a weekend project.
Insurance, Documentation, and the Written Scope
Insurance is almost always in the room, even when the homeowner has not thought about it yet. If the damage came from a burst pipe, an appliance failure, or a storm, the claim probably exists. That means every hour of work, every piece of equipment, and every disposal decision needs to be documented in a way the carrier will accept. We photograph the scene before extraction starts, mid-process, and at completion. We hand the adjuster a moisture log, a scope of work, and a line-item estimate. We bill the carrier directly, so the homeowner never plays messenger between us and the desk adjuster. The homeowner’s job is to answer the door and choose a contractor. Our job is everything else.
Here is the documentation truth most DIY guides skip: a homeowner who self-mitigates a Category 2 or 3 loss has just taken responsibility for the outcome. The insurer will ask why a certified firm was not called. If mold develops later, the insurer may reasonably point to the self-mitigation and decline the mold claim. The $400 saved on a service call can become a $12,000 uncovered mold remediation. That is not a worst-case hypothetical. It is the pattern we see when we are called in as the second contractor, months after the original loss, to fix what the first attempt missed or made worse.
A written scope of work is the single most important protection a homeowner has against being oversold. This trade has a known reputation problem, and it is worst on mold jobs, where a frightened homeowner is told the entire apartment must be gutted. Our standard practice is different. We write the scope, we show the moisture map, we explain what the dry standard is and how we will know when we reach it. If the drywall does not need to come out, we say so. We stand behind that in writing: the 90-Day Done Right Promise, which the team here calls the Keystone Standard. If it is not done right, we make it right. No paperwork battles, no arguing. That guarantee applies to every job, from a small supply-line leak to a full reconstruction after a fire.
True Cost Comparison: DIY vs Professional Restoration
The honest comparison is not between $300 in rental equipment and a $3,500 professional dry-out. The honest comparison is between the full cost of each path, including the failures.
- DIY surface dry, successful: $150-$400 for rental, $30-$80 for cleaning supplies, two to four days of your labor. This only works on small clean-water spills limited to non-porous surfaces.
- DIY surface dry, failed: $150-$400 for rental that did not work, then $2,800-$6,500 for professional mold remediation, plus $1,200-$4,000 for rebuild of the opened walls or flooring. A typical failed DIY dry-out on a 40-square-foot bathroom leak in the Financial District lands around $8,000 to $12,000 all-in, before insurance picks up any portion.
- Professional dry-out, done immediately: $2,400-$4,800 for a standard Category 1 or 2 water loss in a one-to-two room area, including equipment, monitoring, and documentation. Most of this is billable to insurance.
- Professional dry-out, delayed (after a week of self-management): Same starting price, but now the affected area is larger because the water had time to migrate. Add $800-$2,000 in additional demolition and disposal.
- Sewage backup, any size, DIY attempted: This is where the math truly fails. A Category 3 loss requires containment, PPE, antimicrobials, and disposal of porous materials. The DIY attempt usually stops at “I cleaned the visible mess.” The invisible contamination remains. Professional Category 3 cleanup in a Financial District apartment typically runs $4,000 to $9,000. A failed DIY attempt adds medical risk to the financial one.
There is also the value-of-time argument, and for a homeowner who has lived in the same Financial District co-op for twenty years, time matters. A professional crew arrives the same day, often the same visit, and extraction is running within hours. The homeowner’s job is to call, to point at the leak, and to choose the path forward. That is not laziness. It is a decision about risk management, and it is why the Floodline Restoration Co. home page leads with the dispatch board, not a sales desk. Calls are answered by a live person at any hour. No recording, no call-back tag.
Step-by-Step: What a Professional Restoration Actually Looks Like
Homeowners who understand the sequence of a professional restoration are better equipped to choose a contractor and to evaluate whether the job is being done correctly. Here is what we do, from the moment the call comes in from a Financial District address:
- Live call, immediate dispatch. A real person answers. You describe the leak. We tell you what to do right now: shut the valve, clear the area, photograph what you can. A crew is dispatched to your building, and in most Financial District locations we are on site within one to two hours.
- Initial assessment and safety check. The crew leader identifies the water category, confirms the source is stopped or calls the building’s plumber if not, and checks for electrical hazards. In older Financial District buildings, the panel may be in the wet area. We shut power to affected circuits before walking through standing water.
- Moisture mapping and photo documentation. We take baseline readings across the wet area and into adjacent dry areas, including wall cavities, under flooring, and in the air. These readings become the moisture log. Photographs are taken before any equipment is placed.
- Extraction. Standing water is removed using truck-mounted or portable extraction units. In high-rise Financial District buildings, portable units are standard; the water is extracted and removed via the building’s service path, not dumped down a stairwell.
- Demolition of unsalvageable material. Saturated drywall is cut out, baseboards and padding removed, and flooring opened where needed. This is done to the dry standard, not to a guess. If the material measures dry, it stays.
- Drying equipment placement. Airmovers, dehumidifiers, and Injectidry systems where needed. The count and placement are based on the moisture map, not a standard package. Every affected surface gets air movement, including inside wall cavities.
- Daily monitoring. A technician returns every day, takes readings, rotates equipment, and logs the progress. The log is shared with the homeowner and the insurance carrier. When the structure meets the dry standard, the equipment comes out.
- Rebuild. This is where Floodline differs from most restoration firms. The same crew that extracted and dried your apartment rebuilds it. The baseboards, drywall, paint, and flooring are replaced by the people who know exactly what happened to the structure. There is no handoff to a third-party GC, no inherited crew, no new set of subs walking your Financial District co-op with no history of the job.
The Keystone Standard applies to every one of those steps. If the rebuild is not right, we come back and make it right. In writing. No argument.
Common Mistakes to Avoid
- Waiting “a day or two” to see if it dries on its own. It will not. Water in drywall, wood, and insulation has no path to self-dry in a closed Financial District apartment. The 48-hour clock for mold growth starts immediately. Waiting is the single most expensive decision a homeowner makes in a water loss.
- Using bleach on mold. Bleach is not approved for porous materials by any professional standard. It does not penetrate drywall or wood. It kills surface mold and leaves water behind, which feeds deeper growth. A homeowner who bleaches mold has made the situation look better while making it worse.
- Running a rental dehumidifier without airmovers. A dehumidifier pulls moisture from the air. The water in the wall has to move into the air first, and that requires air movement. Running a dehumidifier alone dries the room, not the wall.
- Not photographing before moving anything. The insurance claim begins with the first photo. If the homeowner pushed the soaked couch aside and mopped up before photographing, the documentation is already incomplete. Take photos first, even with a phone, before touching anything.
- Assuming the co-op or condo policy covers everything. In Financial District buildings, the unit owner’s policy typically covers the interior of the unit. The building’s master policy may cover common elements like risers, the building envelope, and sometimes the subfloor. The line between the two is where disputes happen. A restoration firm that bills the carrier directly and provides photo documentation helps settle that line.
- Trusting a contractor who gives a price over the phone without seeing the job. Any firm that quotes a water damage job without a moisture map is guessing. The honest answer is a range with a written scope after inspection. We provide upfront pricing, with no surprises on the bill, but the figure comes from field data, not a call center script.
- Skipping the moisture log. If your contractor cannot show you moisture readings over the course of the drying job, you do not know whether the job is done. We hand the log to the homeowner and the carrier at completion. It is not an add-on. It is the job.
When to Call a Professional
Call if the water came from a sewer line, a sump pit, a river, or any source you cannot confirm as clean. Call if the water covered more than a single room, sat overnight, or reached any drywall, wood flooring, or insulation. Call if you smell mold, see staining, or notice your ceiling or wall is soft. Call if a neighbor’s unit is involved, if your co-op board or condo association is asking questions, or if an insurance claim will be filed. Call if you are not certain the source is fully stopped. And call if you want the job done right the first time, with a written guarantee behind it. Floodline Restoration Co. offers free estimates in Financial District – call (518) 663-6491.
Frequently Asked Questions
A typical clean-water loss in a one-to-two room Financial District unit runs $2,400 to $4,800 for extraction, drying, monitoring, and documentation. Sewage cleanup runs higher, typically $4,000 to $9,000 depending on the affected area and material disposal. Rebuild work is quoted separately after the dry-out is complete. Most of this is billable to your insurance carrier, and we handle that billing directly. Call (518) 663-6491 for an exact quote after we see the moisture map.
Only if the water is clean, the area is under 10 square feet, the surfaces are non-porous, and you can verify the structure is dry within 48 hours using a moisture meter. If any of those conditions fails, a rental fan will dry the surface and leave the water hidden in the structure. That hidden water becomes mold, and the mold bill will exceed whatever the fan rental saved.
Most homeowner and condo policies cover sudden and accidental water damage, such as a burst pipe or appliance failure. Sewage backup coverage is often an add-on endorsement. The key to a covered claim is documentation: photos, a moisture log, and a written scope. We provide all three and bill your carrier directly. The earlier you call, the cleaner the claim.
In most cases, within one to two hours. Calls are answered by a live dispatcher at any hour, every day. A certified crew reaches the job, and extraction is running the same visit. That speed is the difference between a dried-out apartment and a mold remediation project.
If the affected area is under 10 square feet and the moisture source is stopped, a surface cleaning may be sufficient. Anything larger, or anything hidden behind drywall or under flooring, requires containment and removal, not just cleaning. Our assessment starts with a moisture map, not a sales pitch. If you do not need remediation, we will say so, in writing.
We do. Floodline Restoration Co. bills the carrier directly, provides the adjuster with the moisture log and scope of work, and handles the paperwork. You never play messenger between us and the insurance company. Your job is to choose a contractor you can hold accountable. Call (518) 663-6491 to get started.
The Bottom Line
The DIY versus professional decision comes down to one question: can you verify the water is gone, or can you only assume it is gone? Assumption is not a dry standard. In the Financial District’s pre-war buildings, where water migrates through concrete slabs, raised floors, and shared walls, assumption is how a $400 cleanup becomes a $10,000 remediation. Professional restoration costs more on day one and far less over the following twelve months. The equipment is stronger, the documentation is real, the insurance billing is direct, and the work is backed by the 90-Day Done Right Promise. We have served local communities for over 42 years and answered the phone with a live person every hour of it. If you are standing in water or staring at a stain, call (518) 663-6491. We will be there when we say.
Written by Curt Bowman, Owner at Floodline Restoration Co., serving Financial District since 2010.